Returns to scale and economies of scale
In the short run, increasing the input of variable factors gives rise to 'returns in the short run'. These returns can be increasing, constant, or diminishing. Economic theory predicts that returns in the short run will eventually diminish, with an upturn in the marginal costs of production. But what happens in the long run?
The long run
In the long run, all factors of production are variable, and none are fixed. When a firm moves into its long run it does so by increasing its scale of production. This means that all factors are increased - more labour and capital and increases in all other factor inputs.
For example, if a restaurant owner in one district of a town or city decides to open a second restaurant across town, then it has entered its long run and is increasing the scale of its operations. If over the next 5 years it opens five more restaurants, we can measure its 'returns' to scale at each point of expansion.
This is done by measuring the output - in meals produced per week - as restaurants are added. We can measure total output (in meals), average output per restaurant, and marginal output [the additional meals from adding each new restaurant]. For convenience, each restaurant is referred to as one unit of expansion - each new restaurant means increases in all the factors.
As is shown below, the output in relation to inputs starts to increase at first, becomes constant, and then diminishes (commonly referred to as decreasing returns to scale to avoid confusions with diminishing returns to variable factors in the short run.
| Restaurants | Total meals | Average meals | Marginal meals |
|---|---|---|---|
| 1 | 1000 | 1000 | 1000 |
| 2 | 2400 | 1200 | 1400 |
| 3 | 4000 | 1333 | 1600 |
| 4 | 5600 | 1400 | 1600 |
| 5 | 7000 | 1400 | 1400 |
| 6 | 8200 | 1367 | 1200 |

The onset of decreasing returns to scale starts first with marginal returns. In this case, meals in the fourth restaurant are 1600 per week, and in the fifth the number drops to 1400 - hence decreasing returns sets in with the addition of the fifth restaurant.
Changes in returns to change reflect the impact of economies and diseconomies of scale.
Economies of scale
Economies of scale are the gains that firms can make in terms of reducing production costs as a result of expansion and which are unavailable to smaller firms.
As firm’s grow, they move into the long run. From a firm’s point of view, the long run refers to a situation when all of the firm’s factors of production can be increased – in other words, all factors are variable and none are fixed. In contrast, the short run is defined as a situation where output can be increased by using more variable factors and where at least one factor of production remains fixed.
19th Century English economist, Alfred Marshall1, provides the first attempt to describe and classify the gains derived from expansion. He argued that they arise from ‘economy of skill, economy of specialised machinery, and economy of materials’ as firms increase their scale of production.
According to Marshall these gains could either arise from ‘the general development of an industry’, which he called external economies – or from those ‘dependent on the resources of individual businesses and the efficiency of their management’, which he called internal economies.
Internal economies
Internal economies of scale are those that arise when a single firm expands its scale of operations. Many of these are associated with increased specialisation resulting from larger scale. Examples of these include:
- Marketing, selling and distribution economies – larger firms can employ specialist marketers who are unavailable to smaller producers. For example, larger firms can employ specialist market researchers, or specialist sales staff and spread the cost over a much greater quantity of output, hence at a lower average cost. Distribution costs per unit can also be reduced through the use of specialist distribution systems and resources (such as dedicated vans and trucks).
- Increased division of labour – dividing up labour to focus on a limited range of tasks is more possible in a larger enterprise with thousands of employees than a in a smaller one with a few employees who must undertake a wider range of tasks.
- Technical economies of scale – firms can benefit from increasing the dimensions of equipment and scale of technology which means that the unit cost of output will fall in comparison with smaller scale production. For example, large textile manufacturers in China can use technology that processes and produces vast quantities of cloth in comparison with small scale producers of hand-made textiles.
- Purchasing (or buying) economies of scale – large firms can exert their monopsony power by purchasing raw materials and hiring labour at a lower cost than smaller rivals. For example, large motor manufacturers can purchase components at a much lower price than smaller producers.
- Research and development (R&D) economies - larger
enterprises can allocate more resources to the research and development of new
(lower cost) products or new processes (which can reduce average costs).
Internal economies not arising from specialisation
- Managerial economies (also called administrative economies of scale) – as firms grow, they can begin to employ management staff over a range of business units and spread the cost. For example, a chain of restaurants may only need one accountant, or one head of IT, with average costs of such staff falling.
- Financial economies of scale – similarly, larger firms can borrow more cheaply at a lower rate of interest. Larger firms are more likely to be able to raise capital than smaller firms.
- Risk-bearing economies – larger firms can take more risk by diversifying their range of products or services, and reduce the impact of poor performance of some of their lines. For example, a large store can stock more lines and bear the cost of any failure more than a smaller store with much less space.
Internal economies derived from increased specialisation
Internal economies of scale reduce average costs and hence provide benefits to the firm, examples including:
- Reducing long run average costs and increasing profits.
- Being able to reduce price and increase competitiveness.
- Making entry into the market difficult.
External economies of scale
External economies of scale are gains that are potentially available to all firms in an industry when the industry itself grows. Examples include:
- Ancillary expertise - as an industry grows it attracts into it increasing numbers of ancillary industries and firms that supply components and expertise, including specialist legal services and financial institutions. Over time, the skills developed by employees will increase as they become increasingly specialised. Two examples are commonly cited are the financial district in the City of London, and the IT industry in the US’s Silicon Valley.
- Growth of knowledge - as an industry grows and firms cluster in one area, knowledge develops and become available for all those in that area.
- Infrastructure - the development of a local infrastructure including transport links is also possible when a localised industry grows.
- Greater bargaining power - large firms can also increase their bargaining power in relation to obtaining favourable subsidies from government.
The Long Run Average Cost Curve (LRAC)
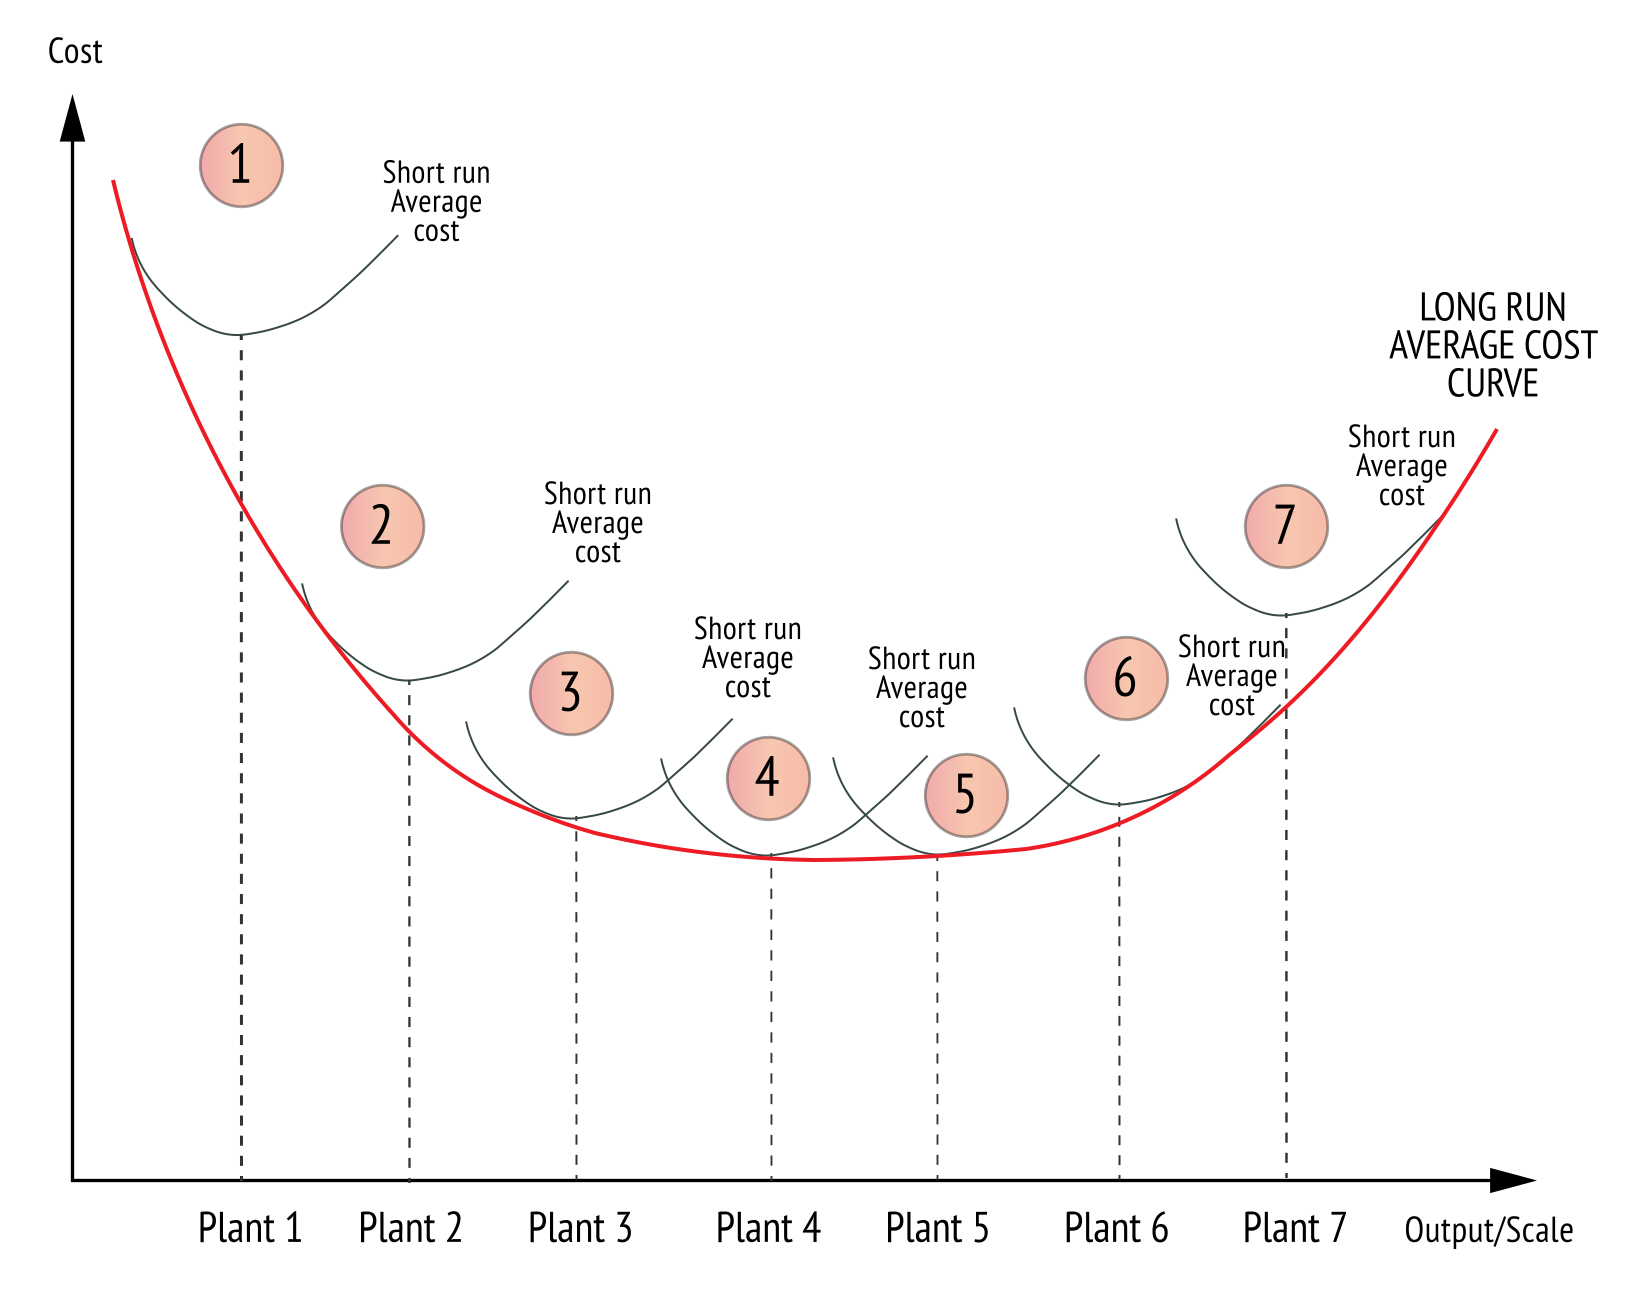
The LRAC curve is derived by tracking the changes in average cost that result from increases in the scale of a firm’s operations. As can be seen in the following hypothetical example, adding new plants results in lower short run cost structures until eventually short run costs begin to rise again.

We can derive the LRAC from drawing a line of tangent to the short run curves, as shown: